EURUSD
- EUR/USD Price: EUR/USD came under fresh selling pressure during Thursday’s Asian session, reversing momentum after the previous day’s modest recovery.
- ECB meeting: The European Central Bank is scheduled to announce its latest monetary policy decision later today, with markets expecting interest rates to remain unchanged. However, the ECB is expected to maintain a hawkish bias, leaving the door open for a potential 25-basis-point rate hike in December.
- French situation: Concerns over France’s mounting public debt and ongoing political gridlock could continue to undermine confidence in the shared currency.
- Q3 GDP: In the United States, investors are looking ahead to the preliminary third-quarter GDP report, with expectations pointing to annualised quarterly growth of 3.4%.
- Norwegian data: Norway’s retail sales fell by 0.4% month-on-month in September, a smaller decline than the 0.7% expected by Danske Bank, following a 0.6% increase in August.
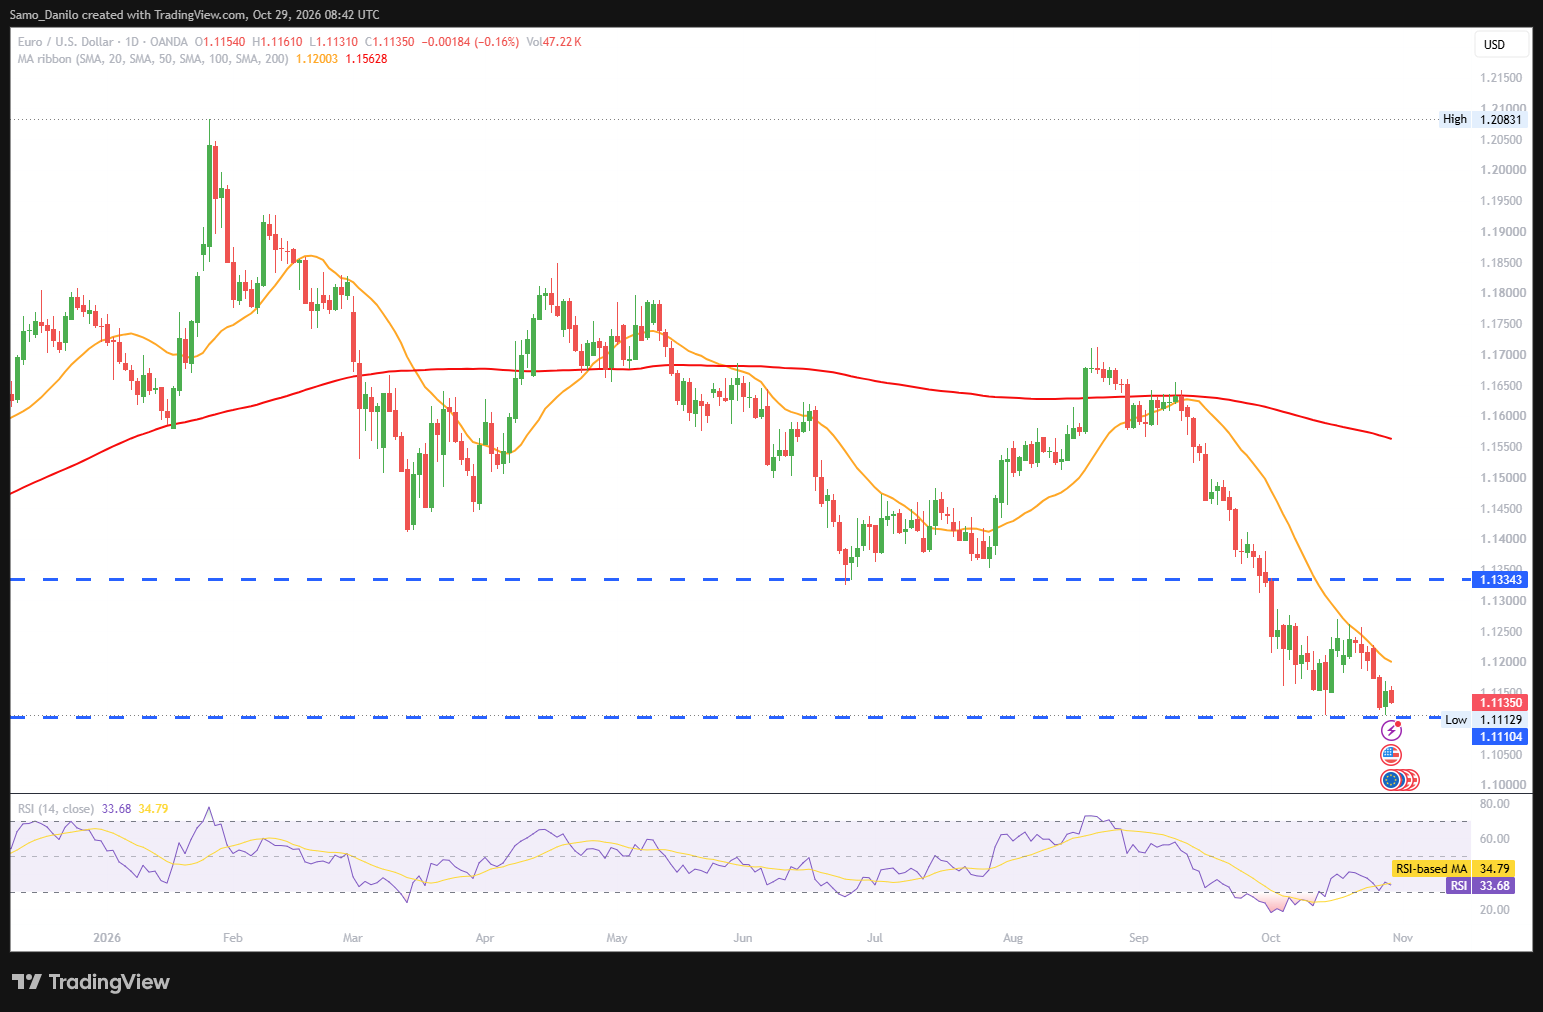
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Falling | | |
Closing statement: EUR/USD remains vulnerable to further downside, with renewed US Dollar demand, French fiscal concerns and political uncertainty weighing on the Euro. The ECB decision and US GDP release will be the key near-term catalysts, with a hawkish ECB stance potentially offering support, while stronger US growth could reinforce bearish pressure on the pair.
GBPUSD
- GBP/USD Price: GBP/USD is trading in negative territory around 1.3320 during Thursday’s early European session.
- UK Budget: Chancellor John Healey presented a Budget that largely matched market expectations, emphasising his commitment to the government's fiscal rules and confirming that the package is fully funded.
- Defence spending: The UK has set a target to increase defence spending to 3% of GDP, with Healey also announcing billions in additional aid for Ukraine. The move was described as a clear message to Moscow, highlighting the government's commitment to strengthening national security and supporting Ukraine.
- BoE rate: UK inflation is expected to average 3.4% next year before gradually returning to the Bank of England’s 2% target towards the end of the decade. The BoE is widely expected to raise interest rates next week, reflecting persistent inflationary pressures in recent months.
- Fed rate: The Federal Reserve kept its benchmark interest rates unchanged within the 3.75%-4.00% range, as widely anticipated. However, policymakers Hammack and Cook dissented in favour of a 25-basis-point rate hike, highlighting concerns over inflation and the potential need for tighter monetary policy.
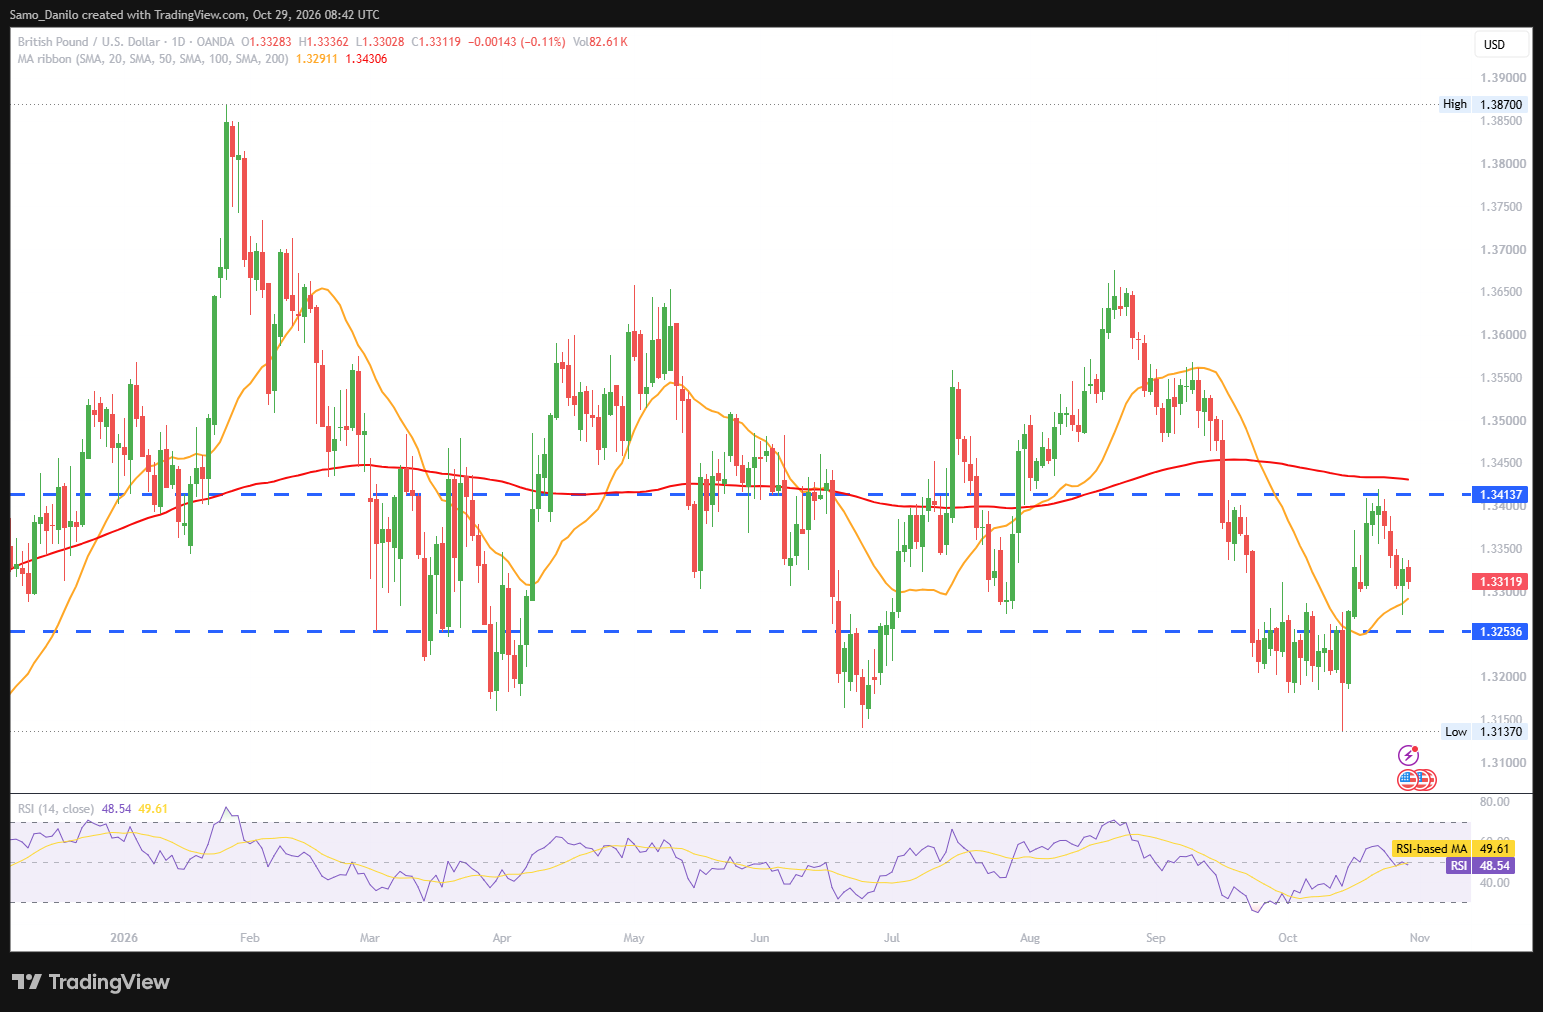
| SMA (20) | Falling | | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Rising |  |
Closing statement: GBP/USD remains under pressure around 1.3320, despite the UK Budget broadly meeting expectations and markets anticipating further BoE tightening. The Fed's decision to hold rates, accompanied by hawkish dissent, may continue to support the US Dollar, while next week's BoE decision will be crucial in determining Sterling's near-term direction.
XAUUSD
- XAU/USD Price: Gold prices have recovered slightly from their daily lows but continue to display an intraday bearish tone below the $4,050 level during Thursday’s early European session.
- Fed path: At the post-decision press conference, Fed official Warsh indicated that US economic growth was probably above 3% in the third quarter. He also highlighted the recent tightening of financial conditions but offered no specific guidance regarding the future direction of interest rates.
- Rate odds: According to the CME Group’s FedWatch Tool, traders are currently assigning approximately an 80% probability to a US interest rate hike at the Federal Reserve’s December policy meeting.
- Bank of Canada: The Bank of Canada raised its benchmark interest rate by 25 basis points to 2.50%, marking its first hike since July 2023. Governor Macklem cited a significantly higher inflation outlook and economic resilience, with the BoC raising its 2027 inflation forecast to 3.1% from 2.0% and increasing its growth forecast for this year to 1.0% from 0.7%.
- Iran tensions: According to The Wall Street Journal, US officials have told several Gulf Arab countries to prepare for a short and intense military campaign against Iran following the November 3 midterm elections.
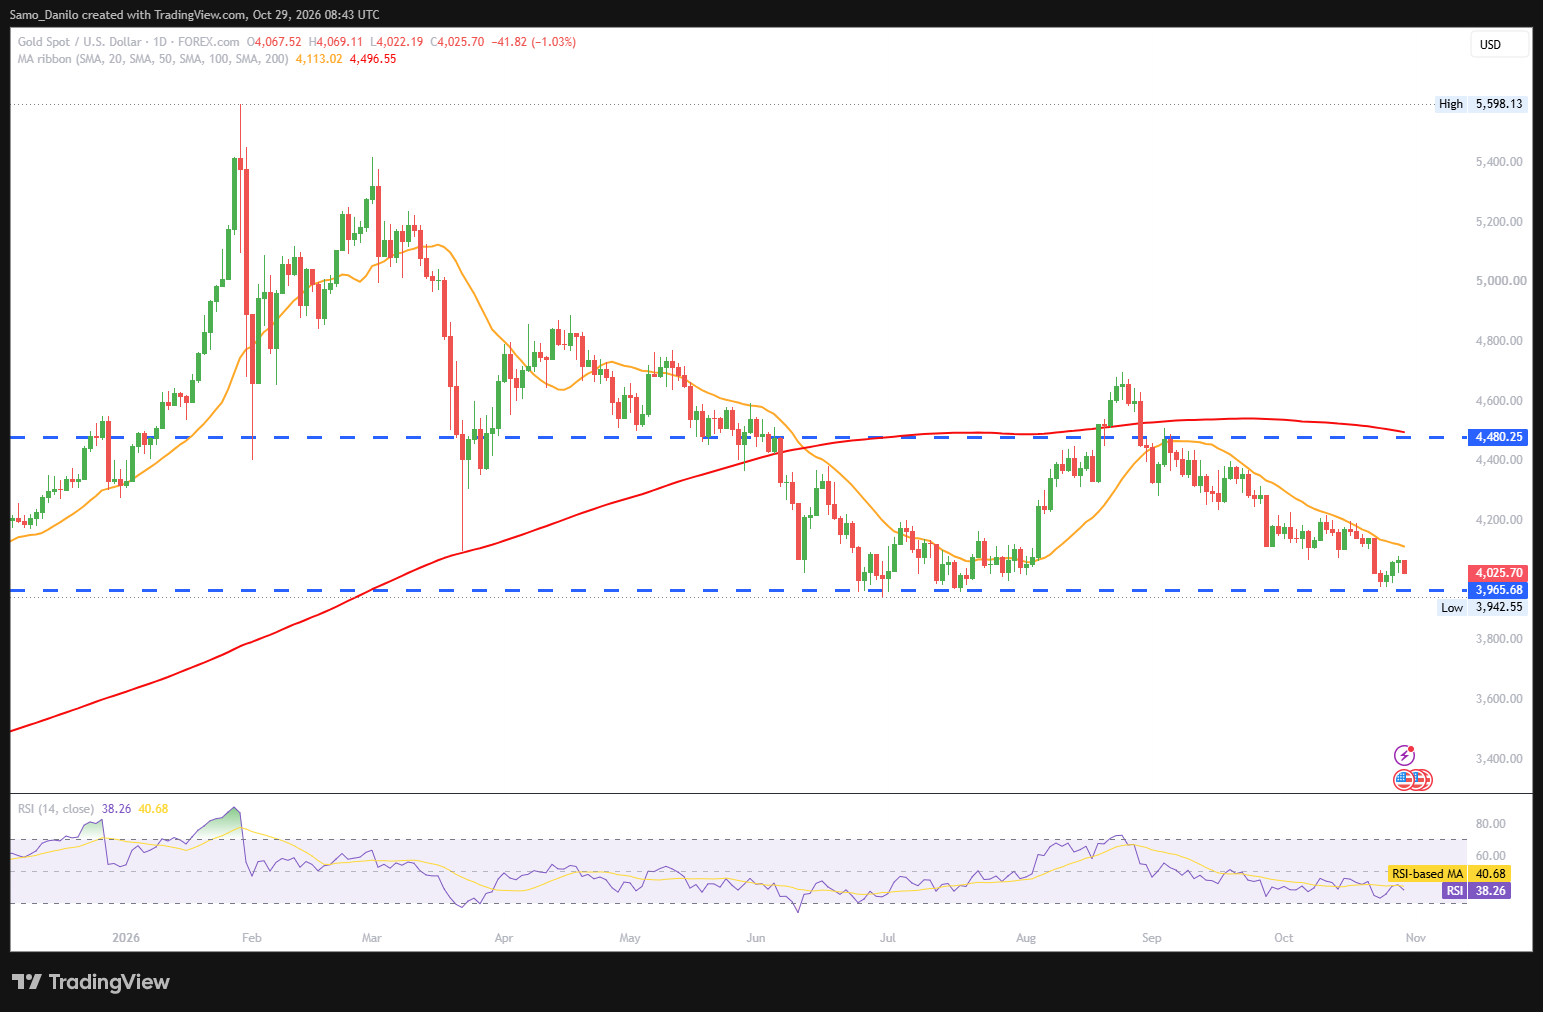
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold remains under bearish pressure below $4,050, primarily due to expectations of a December Fed rate hike and the resulting support for the US Dollar. However, elevated geopolitical tensions surrounding Iran could provide safe-haven support, potentially limiting further losses. The market's focus will remain on Fed expectations and developments in the Middle East for the next directional move.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, is trading around $102.75 during Thursday’s early European session.
- Iran signals: Iranian Foreign Minister Abbas Araghchi stated that the country's armed forces are prepared to defend Iran, while emphasising that Tehran will remain in close contact with intermediaries to give diplomatic efforts a chance.
- Peace negotiations: US Vice President JD Vance reportedly sent a letter to Mohsen Rezaei, secretary of Iran's Supreme National Security Council, in an effort to restart peace negotiations.
- Houthi attacks: The Houthis stated on Tuesday that they had targeted Saudi Arabia's Ras Tanura oil refinery, the largest in the kingdom, using a ballistic missile.
- Inventory data: US Department of Energy data showed crude inventories declining by 1.9 million barrels, compared with expectations for no change, while distillate stocks fell by 1.5 million barrels against an expected 1 million-barrel decline. However, gasoline inventories increased by 3.9 million barrels versus expectations for a 1 million-barrel build, while domestic production rose to 14.0 million barrels per day from 13.3 million previously.
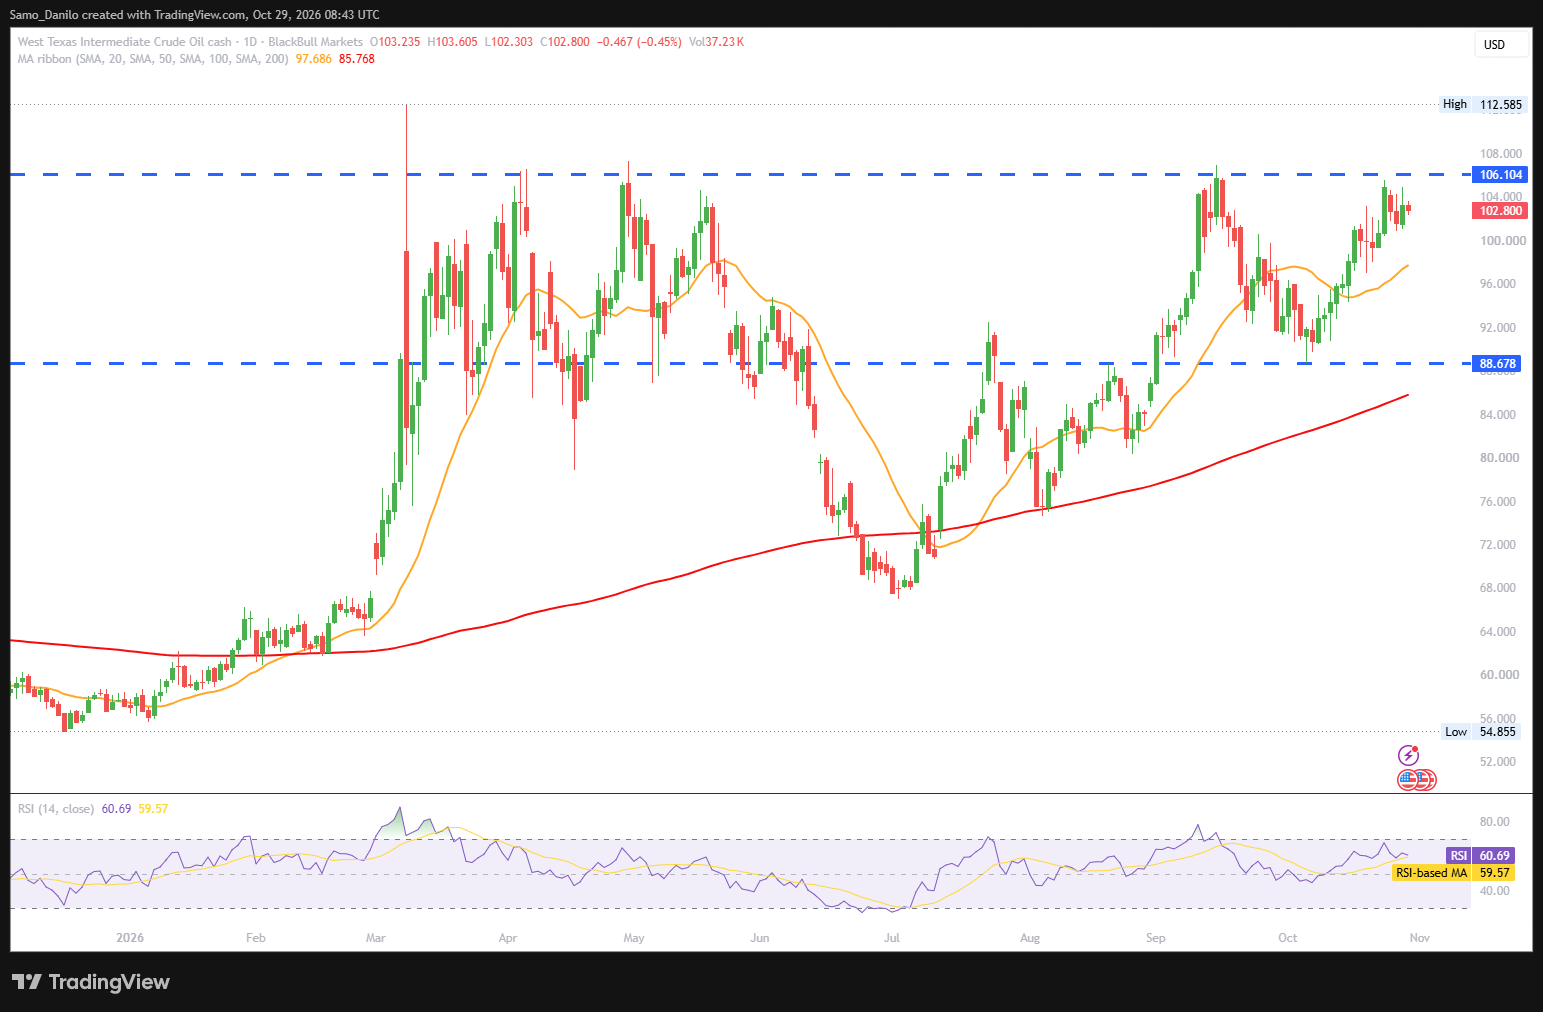
| SMA (20) | Slightly Rising | |
| RSI (14) | Slightly Rising | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI remains supported around $102.75, with Middle Eastern geopolitical tensions and declining crude inventories providing bullish momentum. However, potential progress in US-Iran diplomacy, rising gasoline inventories and higher domestic production could limit further gains. Developments surrounding regional energy infrastructure and diplomatic negotiations will remain key drivers of near-term price action.
DAX
- DAX 40 Price: Germany’s benchmark DAX 40 index is trading around 25,800 points on Thursday morning, reaching its highest level in five weeks.
- EU-Canada: According to Politico, the European Union is reportedly considering scrapping its proposed “associate member” status for Canada in favour of an “ever closer association” framework.
- Rheinmetall news: German defence group Rheinmetall has secured an order to deliver Schakal wheeled infantry fighting vehicles to the German and Dutch armed forces. The contract, awarded through its Artec joint venture with KNDS Deutschland, covers 35 vehicles for Germany and 34 for the Netherlands.
- Italy budget: Italian Prime Minister Giorgia Meloni announced that Italy has approved a €26 billion budget law focused primarily on tax cuts.
- Corporate earnigns: Several major German companies, including DAX constituents Volkswagen, Adidas and MTU, are scheduled to report their quarterly financial results on Thursday morning.
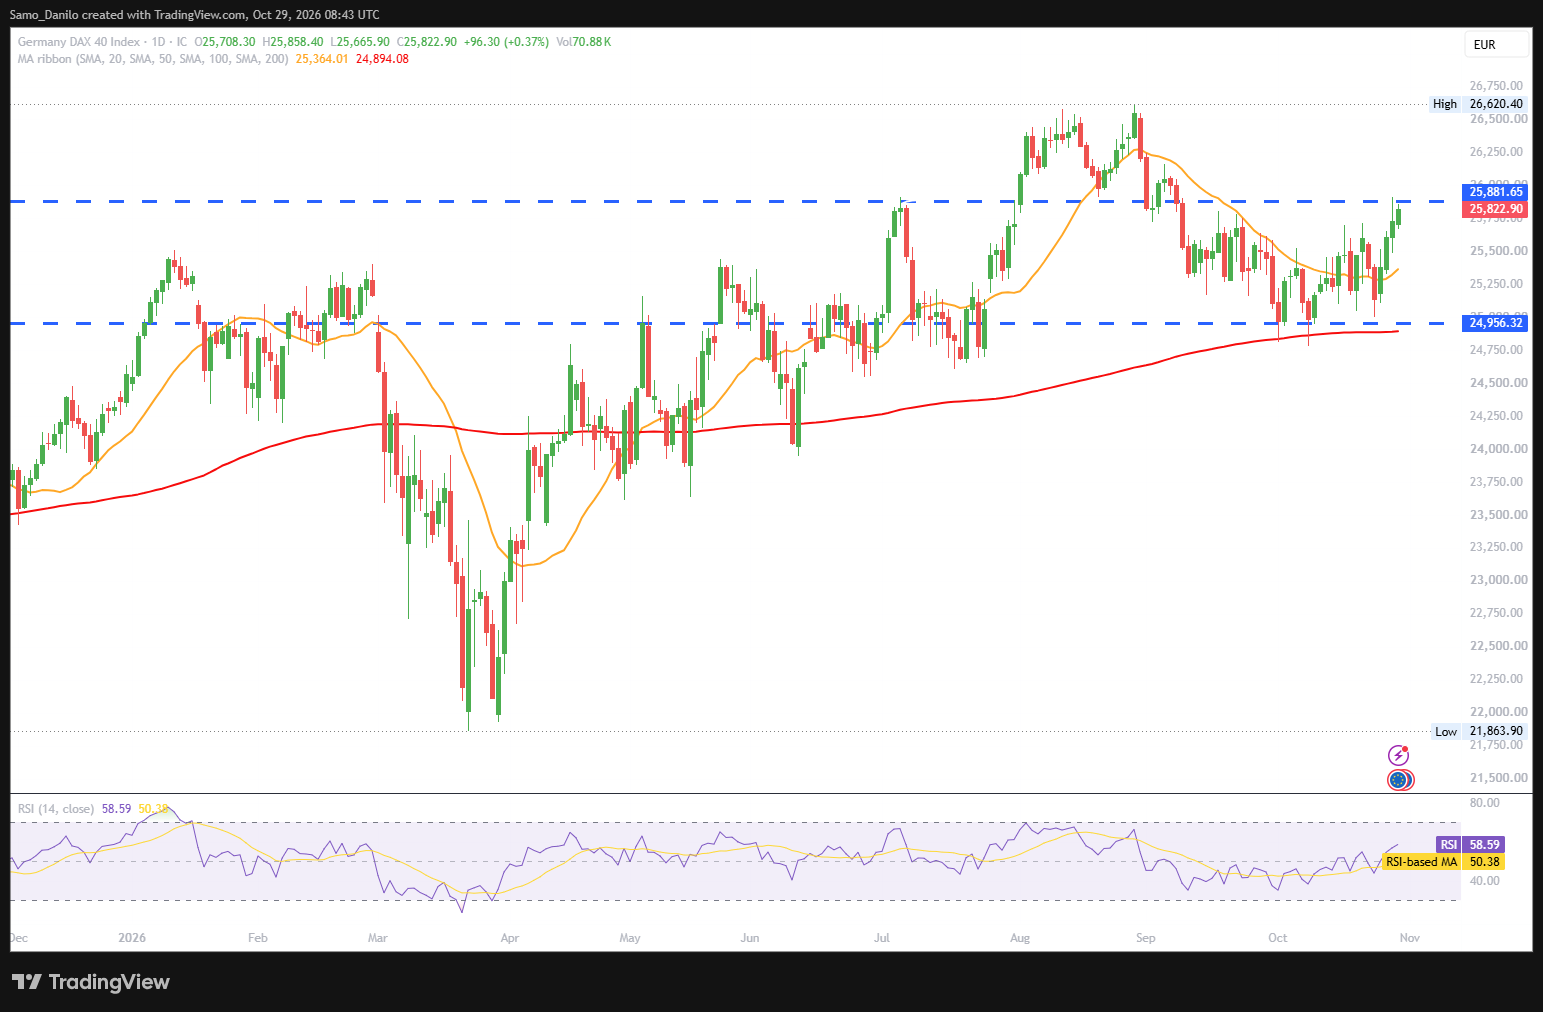
| SMA (20) | Slightly Falling | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: The DAX 40 is showing positive momentum around 25,800 points, supported by its highest level in five weeks and developments in the defence sector. However, the upcoming corporate earnings from major index constituents will be crucial in determining whether the rally can continue, with stronger-than-expected results potentially providing further upside momentum.