EURUSD
- EUR/USD Price: The EUR/USD pair is trading lower near 1.1120 during Wednesday's early European session.
- Lending conditions: The ECB's Q3 Bank Lending Survey revealed that banks tightened credit standards more than expected, although the net share reporting tighter conditions remained relatively low by historical standards.
- ECB meeting: The European Central Bank is widely expected to leave its key interest rates unchanged at Thursday's policy meeting, following the 25-basis-point hike delivered in September.
- French Budget: Budget negotiations in France are making limited progress, with more than 2,800 amendments out of approximately 3,400 still requiring examination as discussions on the revenue side resume. The parliamentary divisions make approval through the normal legislative procedure before year-end increasingly difficult, raising the possibility that the government will invoke Article 49.3 and potentially face a no-confidence vote.
- Fed policymakers: Most central Federal Open Market Committee members have indicated that they can wait until December before considering another rate hike, although some policymakers see a greater need for immediate action.
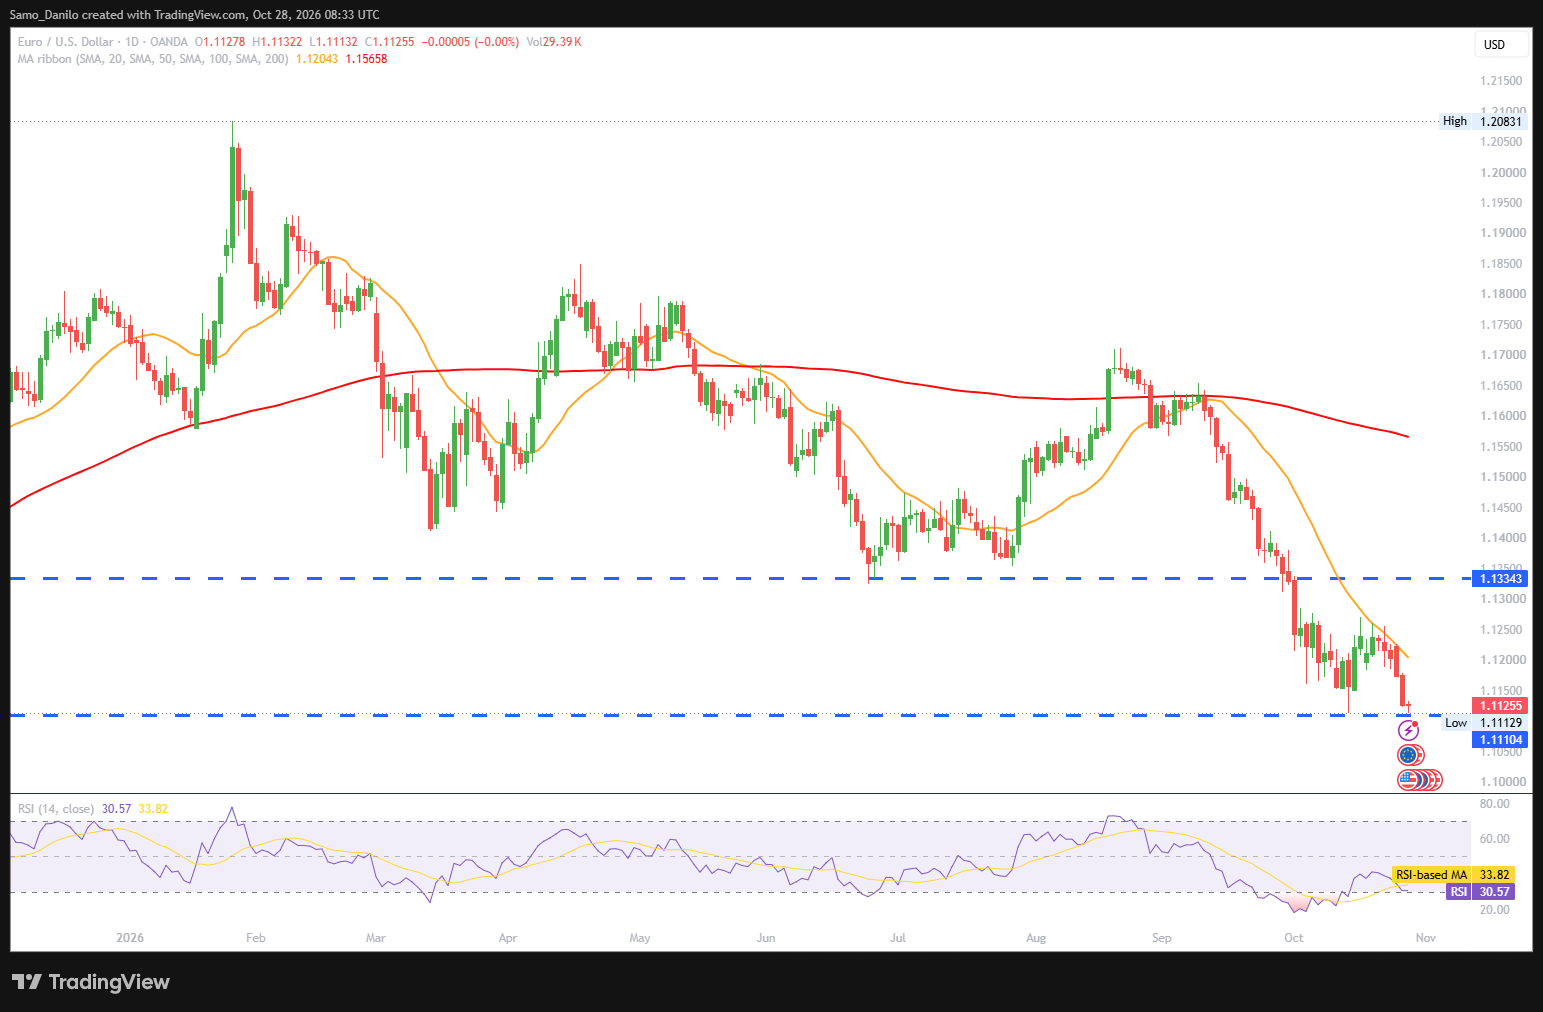
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: EUR/USD remains under bearish pressure near 1.1120 as tighter bank lending conditions, French political uncertainty and expectations of a cautious ECB weigh on the euro. In the near term, the pair's direction will largely depend on Thursday's ECB decision and the evolving outlook for US interest rates, with policy divergence potentially creating further downside risks for EUR/USD.
GBPUSD
- GBP/USD Price: GBP/USD is extending its decline for the fourth consecutive trading day, trading around 1.3290 during Wednesday's European session.
- Autumn Budget: UK Chancellor John Healey is set to present his first Budget today at approximately 13:30 CET, accompanied by the Office for Budget Responsibility's updated Economic and Fiscal Outlook.
- Consumer surveys: New polling suggests that two-thirds of Britons are pessimistic about the future of the UK economy, while 70% expect tax increases in Healey's Budget.
- Consumer confidence: The Conference Board's Consumer Confidence Index increased to 91.7 in October, significantly exceeding consensus expectations of 81.0 and the revised September reading of 84.2.
- Military action: The Wall Street Journal reported on Tuesday that the United States has told several Gulf Arab countries to prepare for a short and intense military campaign against Iran following the November 3 midterm elections.
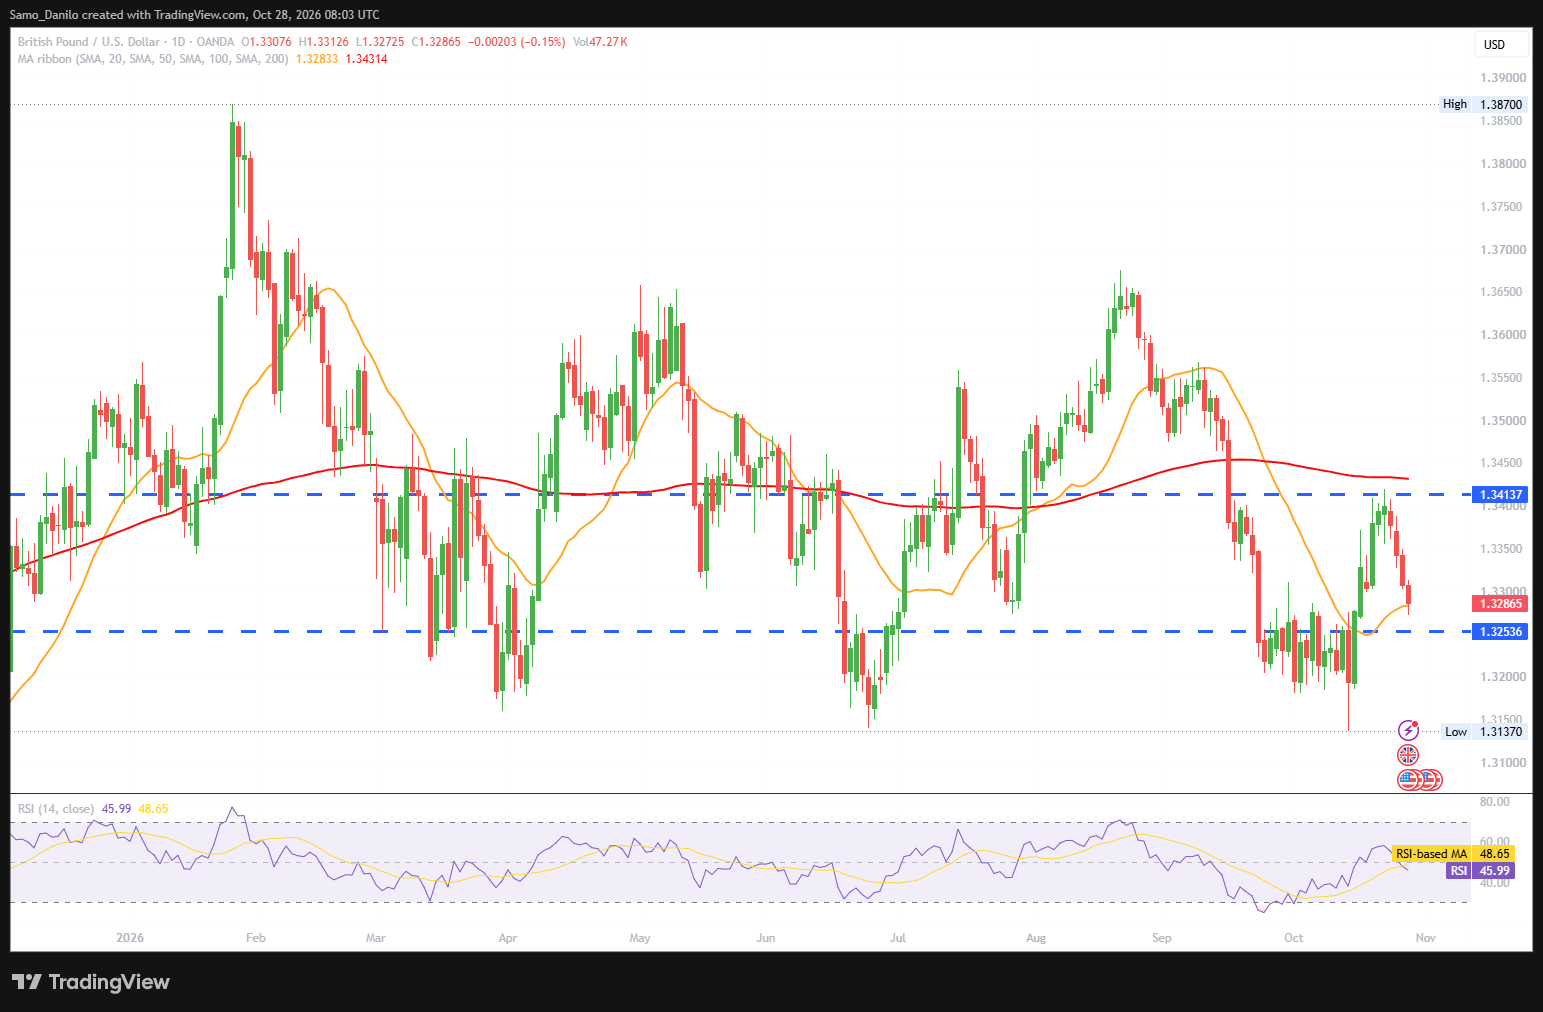
| SMA (20) | Falling | | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Rising |  |
Closing statement: GBP/USD remains under pressure near 1.3290, extending its losing streak for a fourth consecutive day as uncertainty surrounding the UK Budget weighs on sterling. In the near term, the UK Budget and the OBR's fiscal projections will be crucial for sterling, while developments in US-Iran relations and the broader dollar outlook could determine whether the pair extends its decline.
XAUUSD
- XAU/USD Price: XAU/USD remains offered below the $4,050 level during Wednesday’s early European session, snapping a two-day winning streak.
- Fed rate: Markets broadly expect the Fed to maintain its benchmark interest rate within the 3.75%-4.00% range on Wednesday. The central bank’s statement and subsequent commentary will be closely monitored for clues about the future direction of monetary policy.
- Israel elections: Exit polls from Tuesday’s general election indicate a political deadlock, with neither Benjamin Netanyahu’s bloc nor the opposition led by Gadi Eisenkot securing the 61 seats required for a parliamentary majority. Final results are expected on Thursday or Friday, prolonging uncertainty over the country's political outlook.
- Brazil elections: Defeated presidential candidate Flávio Bolsonaro has arrived in the United States after leaving Brazil, where he is under investigation for alleged corruption and money laundering, allegations he denies. His passports were cancelled after he failed to comply with a Supreme Court order to surrender them.
- AI industry: Google could announce a chip purchase agreement with OpenAI as the AI company seeks to reduce its reliance on Nvidia, according to The Information. The development comes as Alphabet is scheduled to hold its quarterly conference call on Wednesday to discuss its third-quarter 2026 financial results.
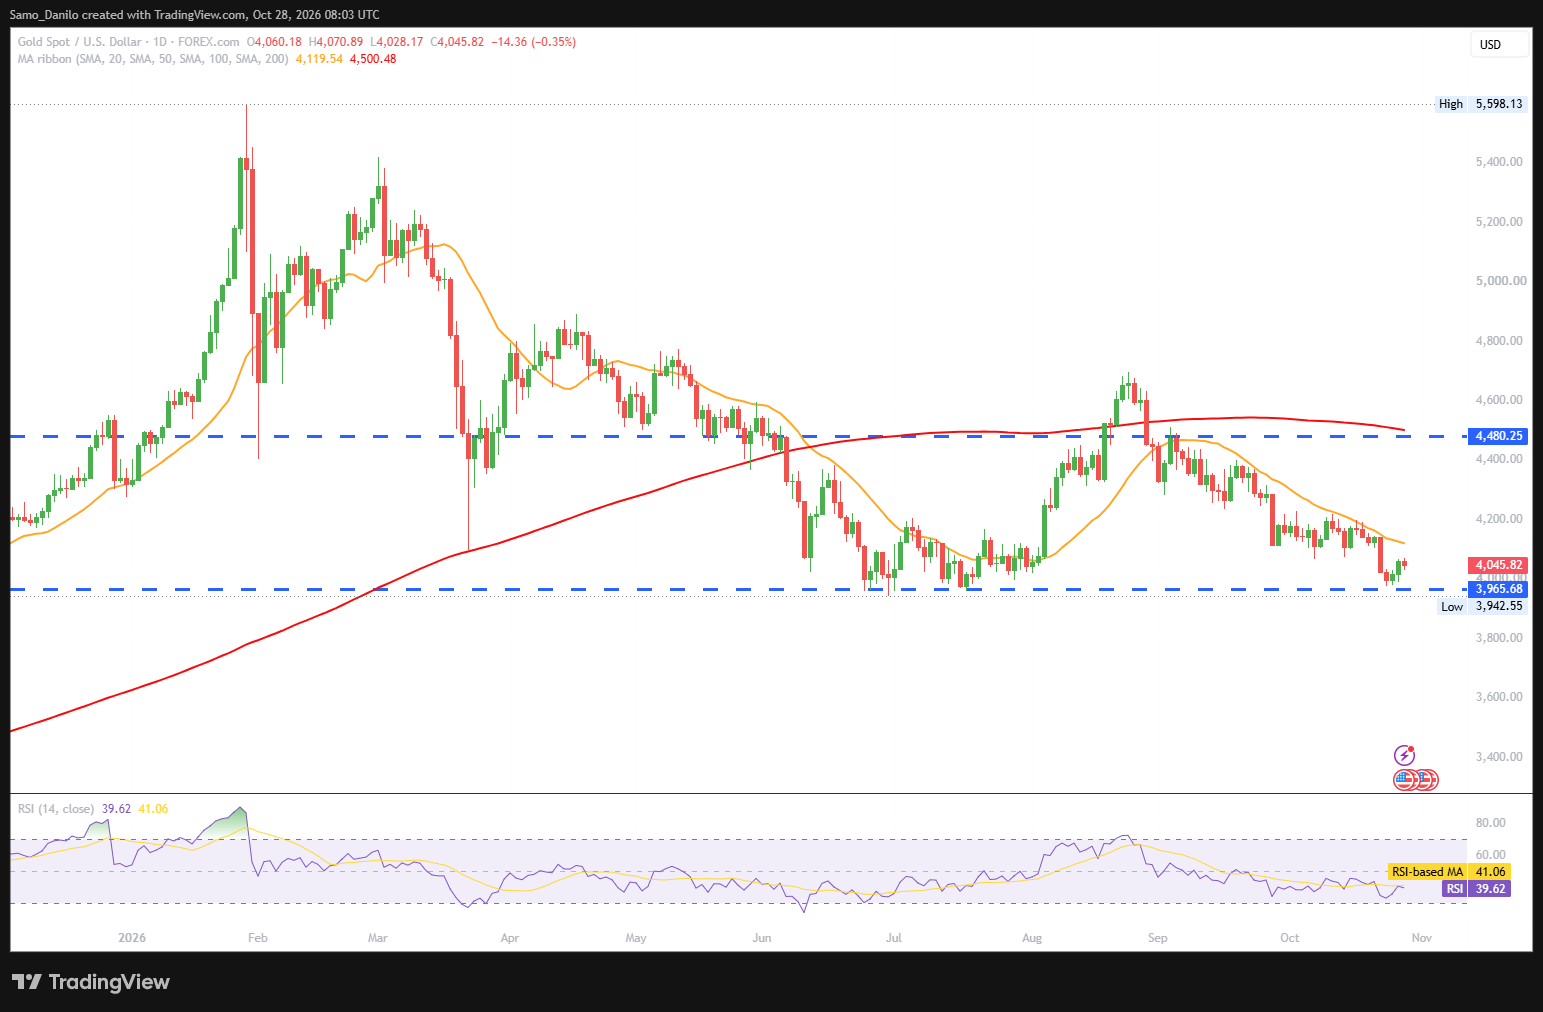
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold remains under pressure ahead of the Fed decision, with expectations of unchanged interest rates potentially limiting immediate price movements. The Fed’s forward guidance and broader geopolitical developments could determine the next directional move, while a more hawkish policy outlook may add further downside pressure to the precious metal.
CRUDE OIL
- Crude Oil Price: West Texas Intermediate (WTI), the US crude oil benchmark, is trading around $102.75 during Wednesday’s early European session.
- Iran tensions: In his post-election speech, Israeli Prime Minister Benjamin Netanyahu raised the possibility of renewed joint action with US President Donald Trump against Iran.
- Crude inventories: American Petroleum Institute (API) data showed that US crude inventories fell by approximately 2 million barrels last week, suggesting tighter domestic supply conditions.
- OPEC+ production: Market expectations suggest that OPEC+ producers will keep their current production targets unchanged at this weekend’s meeting. Such a decision would indicate continued supply discipline among major oil-producing nations.
- EIA report: Traders are now turning their attention to the Energy Information Administration’s (EIA) weekly crude oil stockpiles report, due later on Wednesday.
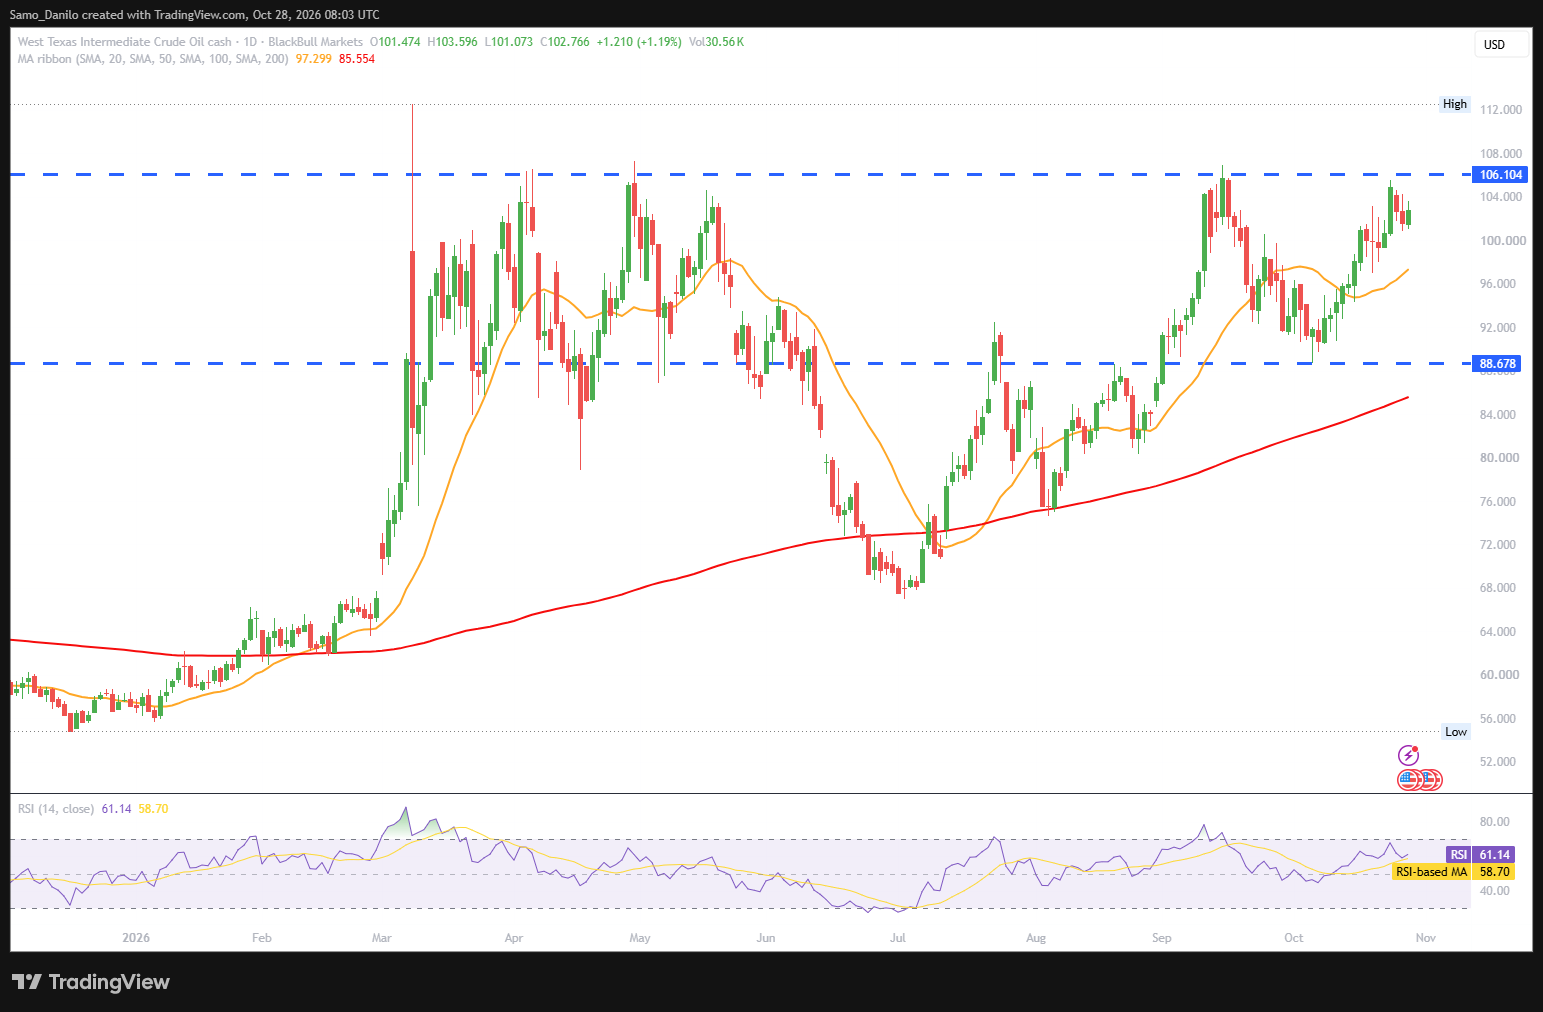
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI remains supported around $102.75, with geopolitical risks involving Iran and declining US crude inventories providing bullish momentum. However, the upcoming OPEC+ meeting and EIA report could influence the near-term direction, with further inventory declines potentially supporting prices, while a surprise build could trigger a pullback.
DAX
- DAX 40 Price: Germany’s benchmark DAX 40 index is trading lower at around 25,500 points during Monday’s morning session.
- Global tax: According to Politico, the European Union is exploring a global tax deal targeting multinational companies as a potential source of additional revenue for its next budget.
- Ukraine-Russia talks: The leaders of Finland and Norway held a rare call with Russian President Vladimir Putin ahead of planned US-brokered talks between Ukraine and Russia in Abu Dhabi in November. Although coordinated with Kyiv, the initiative has yet to show signs of progress, while Russian Foreign Minister Sergei Lavrov warned that the conflict was likely to continue and escalate.
- Mercedes-Benz news: Mercedes-Benz plans to introduce a new voluntary buyout programme for support staff as part of its broader efficiency drive.
- Volkswagen news: Growing competition, particularly from China, alongside steep US tariffs, has forced Volkswagen CEO Oliver Blume to pursue a major corporate overhaul. The restructuring could involve around 100,000 job cuts globally and the closure of up to four factories in Germany, potentially marking one of the largest corporate restructurings in the industry.
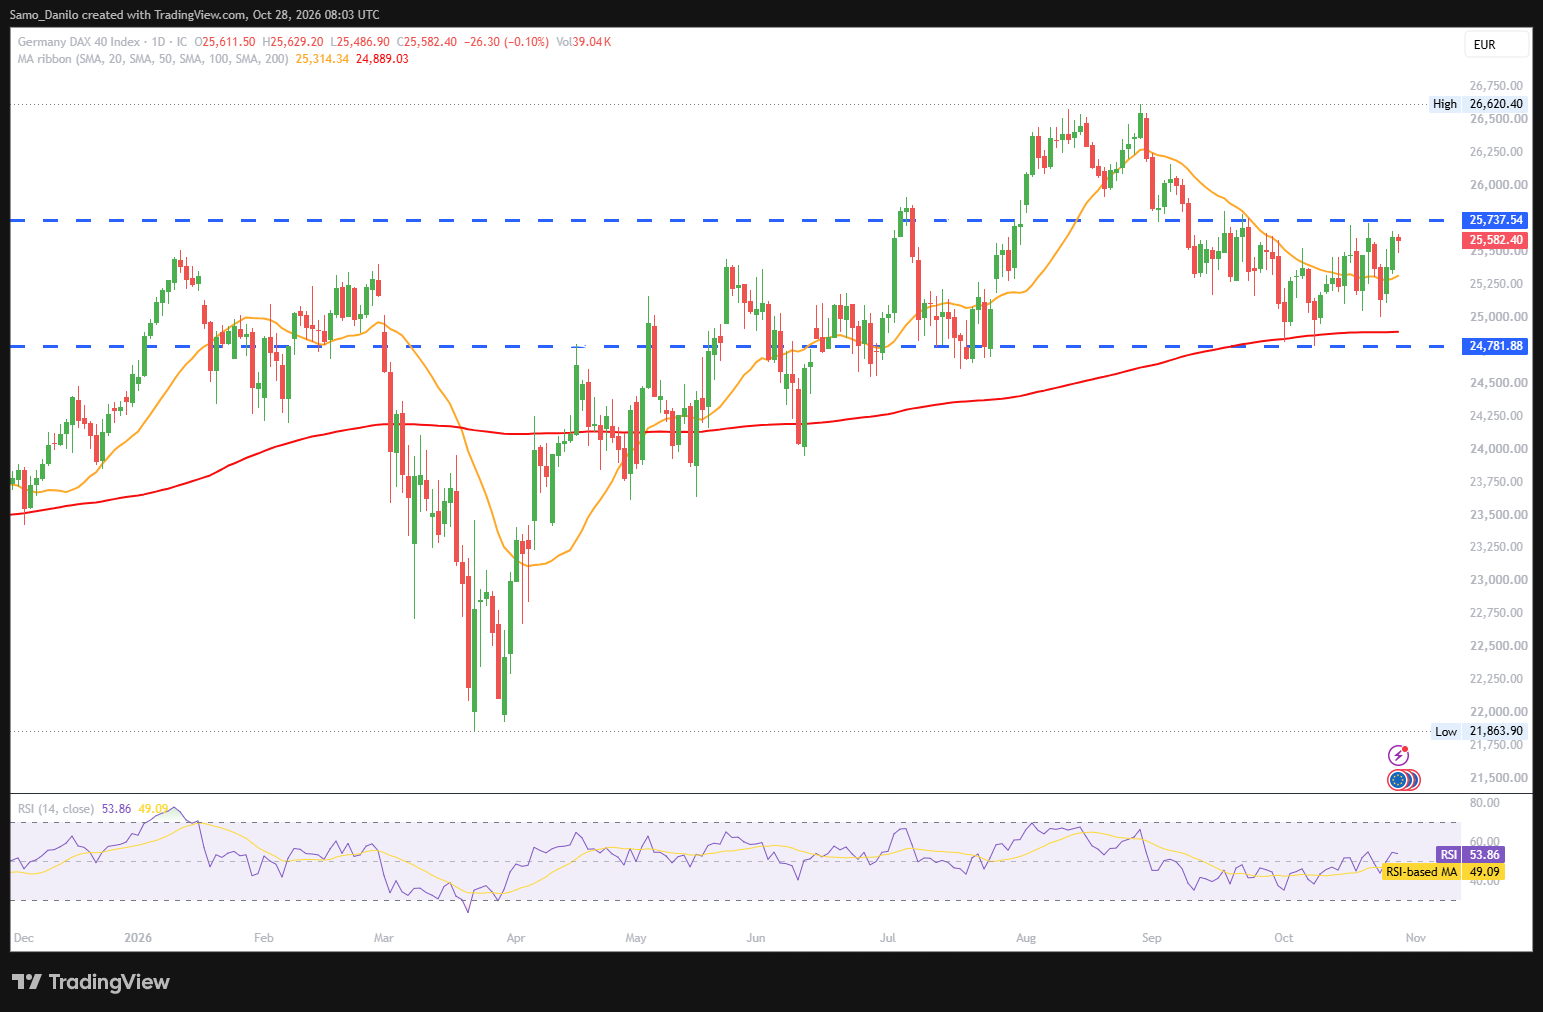
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Rising | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 faces pressure from geopolitical uncertainty and mounting challenges across Germany’s automotive sector. While potential progress in Ukraine-Russia negotiations could improve sentiment, continued trade pressures, restructuring concerns and broader economic uncertainty may weigh on the index in the near term.