EURUSD
- EUR/USD Price: The EUR/USD pair is trading in negative territory near 1.1165 during Tuesday's early European session.
- ECB lending: The European Central Bank is set to publish its Q3 Bank Lending Survey, providing insight into how credit standards and lending conditions across the euro area have changed over the quarter.
- Data centres: Spain is reportedly preparing to ease its proposed data centre regulations by increasing the power-capacity threshold for affected facilities from above 1 MW to above 10 MW, according to US financial press reports.
- ECB rate: According to a Reuters poll, the ECB is likely to leave its deposit rate unchanged at 2.50% at Thursday's October policy meeting, before delivering a 25-basis-point rate hike in December.
- Market ahead: Traders will closely monitor the Federal Reserve and European Central Bank interest rate decisions later this week.
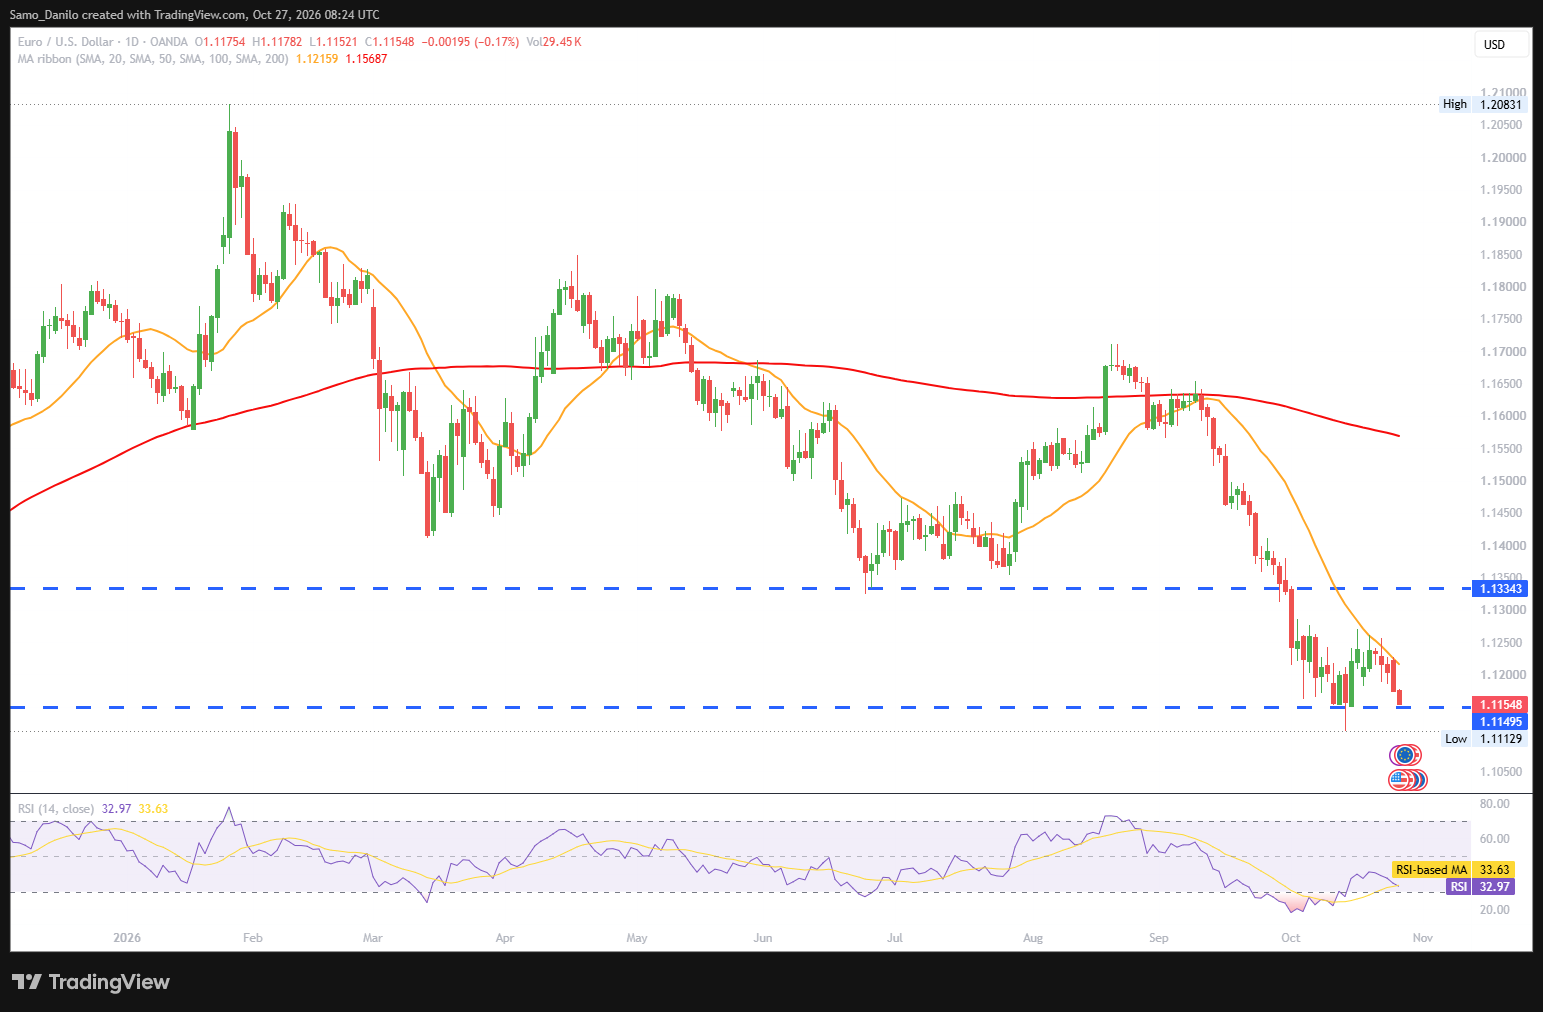
| SMA (20) | Falling |  | |
| RSI (14) | Falling | | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: EUR/USD is trading lower near 1.1165 as investors position themselves ahead of a crucial week for monetary policy. Expectations that the ECB will hold rates steady in October but consider a December hike could provide some medium-term support for the euro, particularly if inflation remains elevated. However, the pair's near-term direction will largely depend on the tone of the Fed and ECB announcements, with any more hawkish signals from the Fed potentially adding further downside pressure to EUR/USD.
GBPUSD
- GBP/USD Price: The GBP/USD pair is trading lower near 1.3335 during Tuesday's early European session.
- Autumn Budget: New UK Finance Minister John Healey is set to deliver his first budget on Wednesday, against a backdrop of rising global borrowing costs and elevated energy prices linked to the Iran war.
- Retail indicators: The UK October CBI Retailing Reported Sales improved to -10 from -55 previously, indicating a less negative assessment of retail activity. Meanwhile, the BRC Shop Price Index rose to 2.1% year-on-year from 1.6%, reaching its highest level since February 2024 and highlighting continued pressure on retail prices.
- Consumer confidence: The Conference Board is due to release its October consumer confidence report, following a notable decline to 81.9 in September.
- Key events: Traders are largely staying on the sidelines and avoiding significant positions ahead of Wednesday's UK Autumn Budget and Federal Reserve interest rate decision.
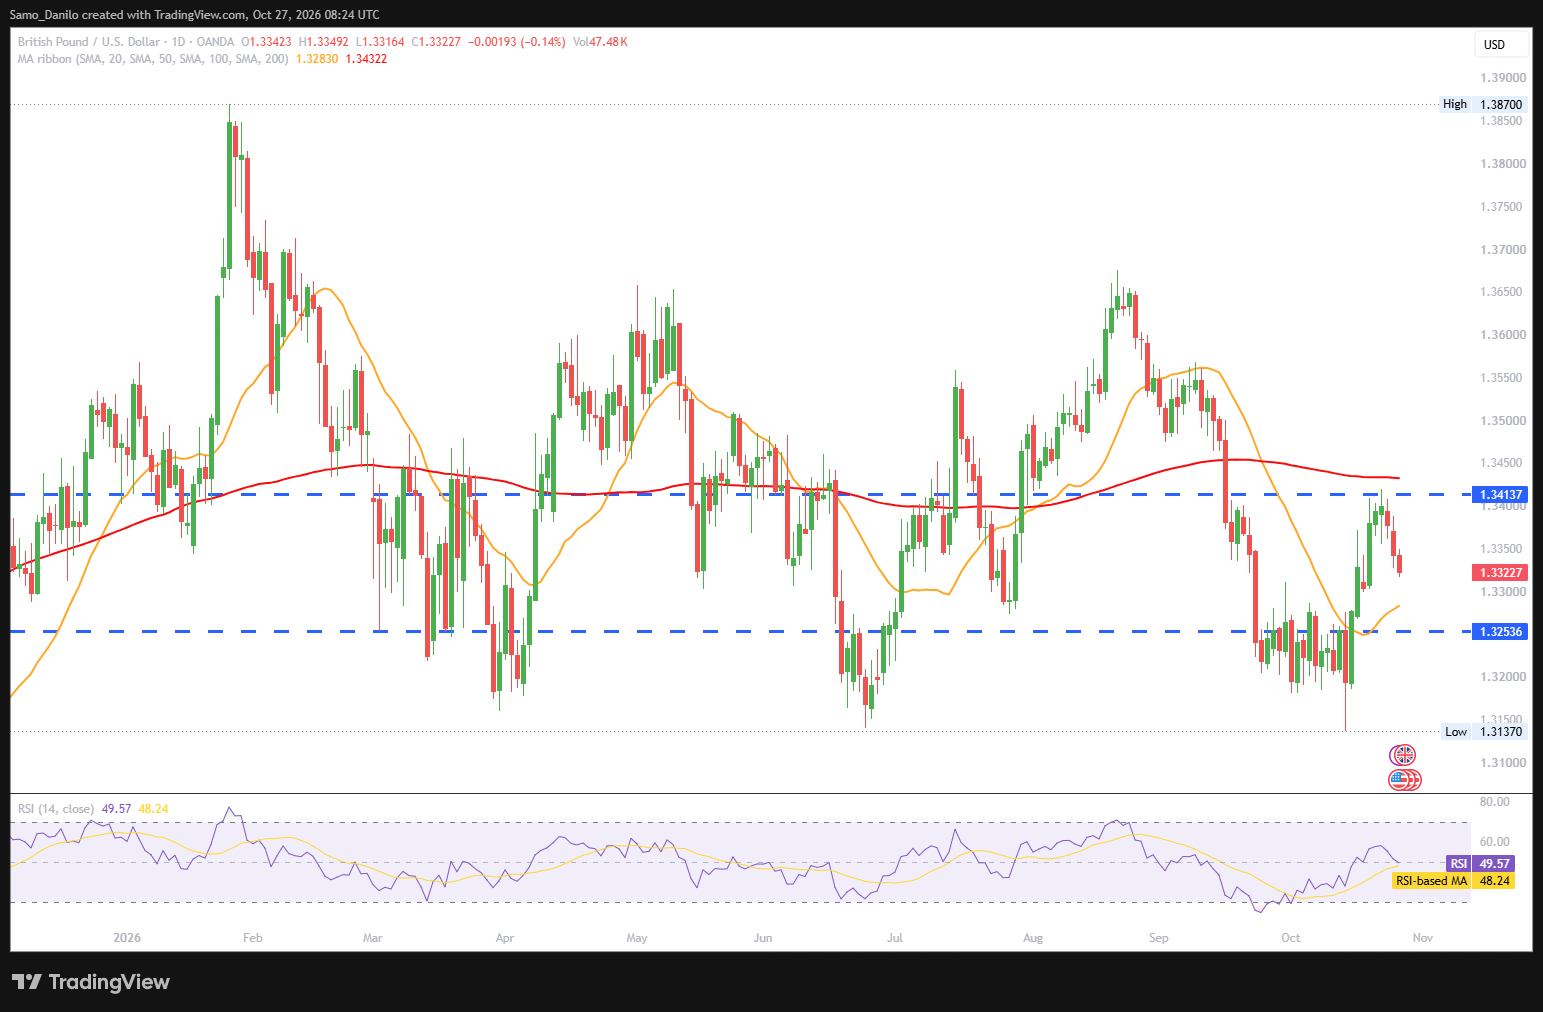
| SMA (20) | Falling | | |
| RSI (14) | Slightly Falling | |
|
| MACD (12, 26, 9) | Slightly Rising |  |
Closing statement: GBP/USD is trading lower near 1.3335 as markets remain cautious ahead of Wednesday's major UK and US events. The pair's near-term direction will largely depend on the government's fiscal announcements and the Fed's policy guidance, with a more hawkish Fed stance potentially adding further pressure on GBP/USD.
XAUUSD
- XAU/USD Price: Gold (XAU/USD) remains under pressure heading into Tuesday's European session, with bearish traders looking to extend the decline further below the key psychological $4,000 level.
- Israeli election: Voters in Israel are heading to the polls in a general election, with final opinion polls indicating that neither Prime Minister Benjamin Netanyahu's coalition nor the opposition is expected to secure a parliamentary majority.
- Chinese profits: China's industrial profit growth accelerated to 14.4% year-on-year in September, up from 4.2% in August.
- Anthropic news: Artificial intelligence company Anthropic has reportedly filed for a potentially record-breaking IPO on Nasdaq, with a listing expected before Thanksgiving. Some investors are reportedly valuing the AI company at approximately $1.5 trillion, highlighting continued investor interest.
- Interest rates: According to the CME FedWatch Tool, traders are pricing in nearly an 89.5% probability that the Federal Reserve will leave interest rates unchanged within the current target range of 3.75%-4.00%.
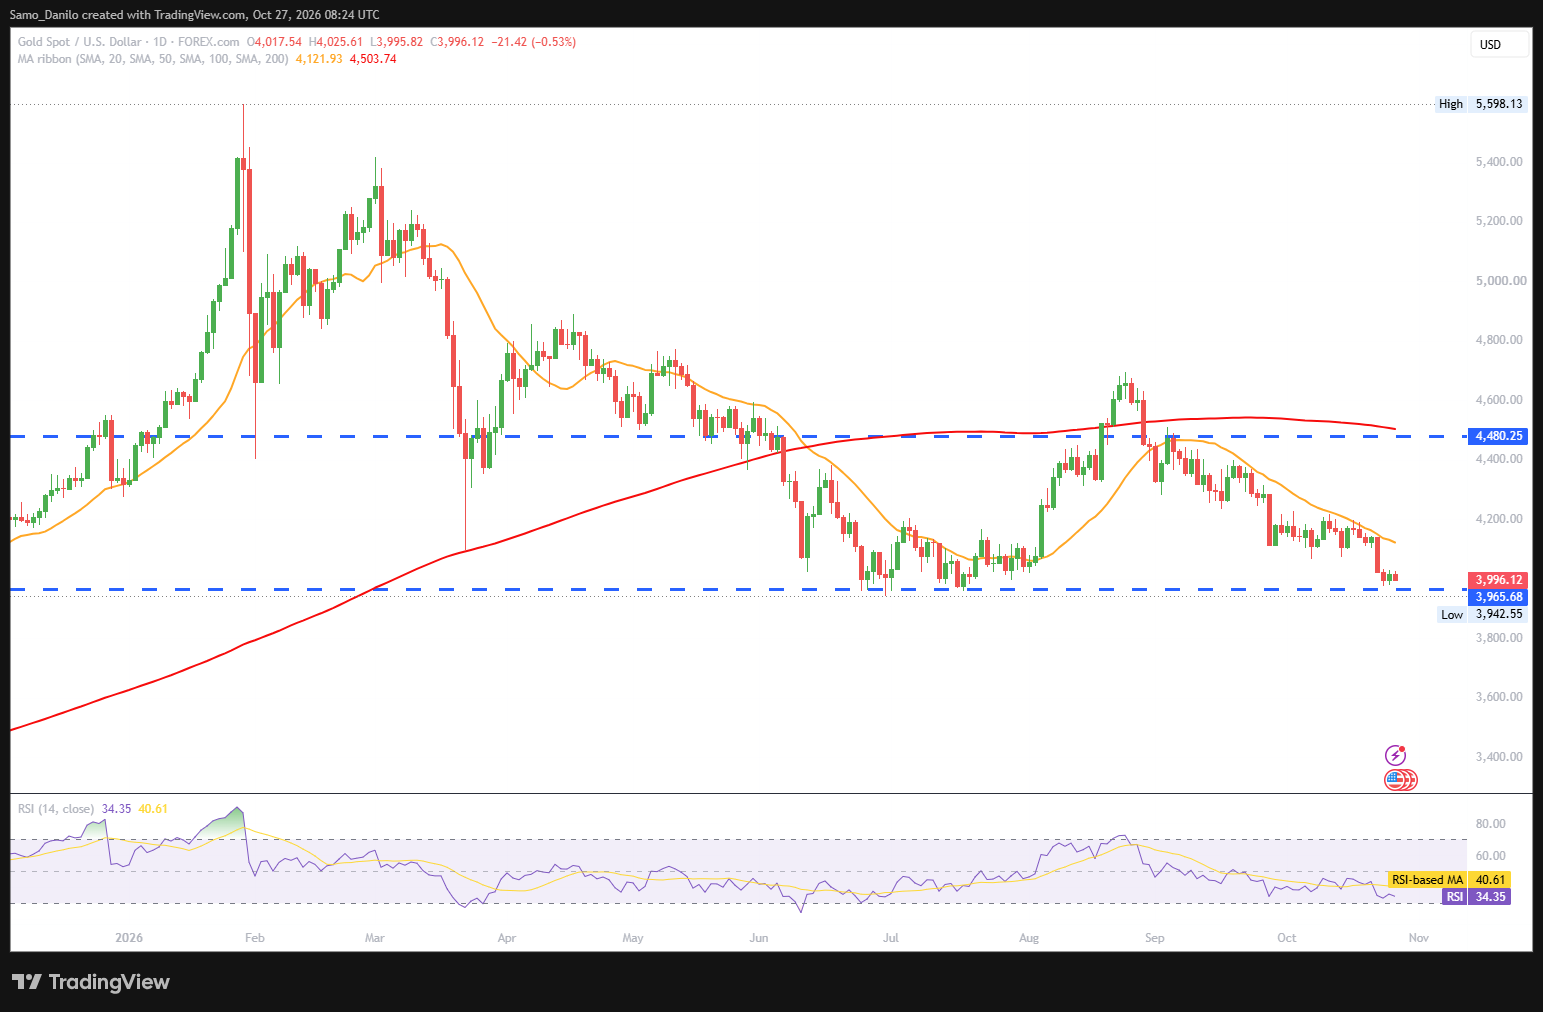
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: Gold remains under significant bearish pressure as a stronger US dollar and expectations of unchanged Federal Reserve interest rates weigh on the precious metal, with traders watching whether prices extend their decline below the $4,000 psychological level. In the near term, gold's direction is likely to remain closely tied to dollar movements, US interest rate expectations and geopolitical developments.
CRUDE OIL
- Crude Oil Price: Crude oil is trading lower at around $103.70 during Monday's European session.
- Regional cooperation: Iran, Turkey, Pakistan and Saudi Arabia have reportedly agreed to strengthen regional cooperation and continue discussions on security, regional unity and shared concerns over Israel's policies and the ongoing conflict between the United States and Iran.
- Trade tariffs: The United States and Canada are reportedly working on an agreement to ease US Section 232 tariffs on Canadian steel and automobile imports. The deal could be reached before the November 3 midterm elections, potentially improving trade relations and reducing uncertainty surrounding North American industrial activity.
- Russia strikes: Russia's Defence Ministry reportedly announced a suspension of strikes on Ukraine's Kherson region as a ceasefire begins in Oleshky.
- IEA highlights: International Energy Agency Chief Fatih Birol warned that geopolitics will play a much more pronounced role in global energy markets, underscoring the importance of energy security.
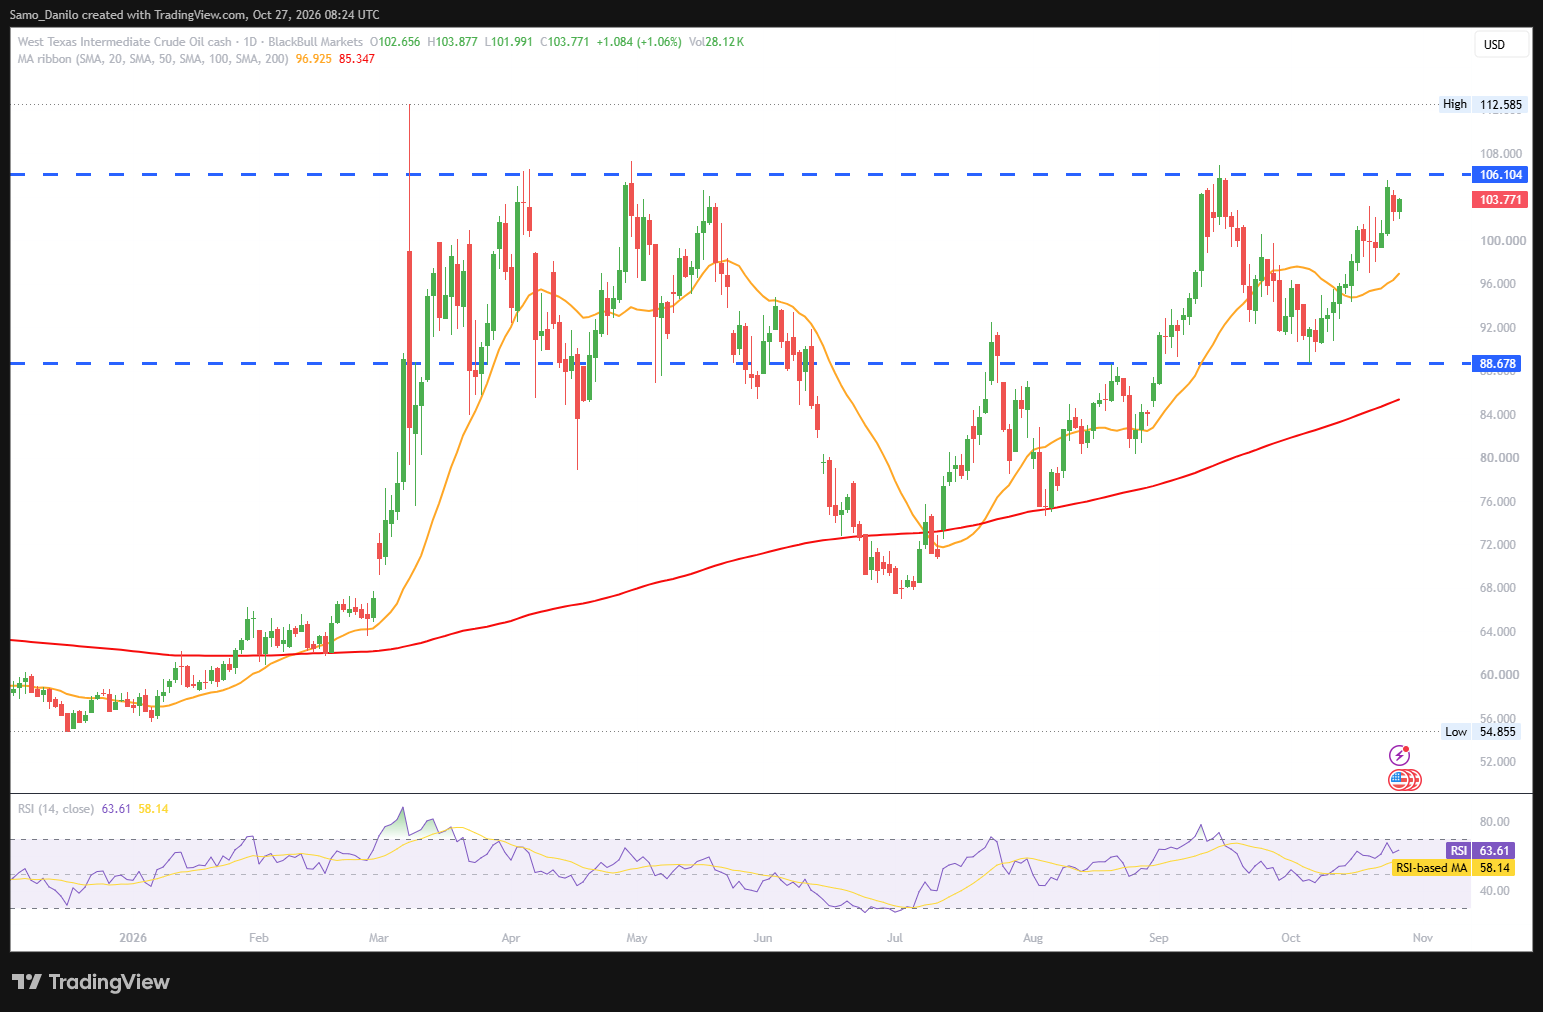
| SMA (20) | Slightly Rising | |
|
| RSI (14) | Rising | | |
| MACD (12, 26, 9) | Slightly Rising | |
Closing statement: WTI is trading lower near $103.70 as diplomatic initiatives and reports of reduced military activity provide some potential relief from geopolitical concerns. In the near term, crude oil is likely to remain highly sensitive to developments in the Middle East, with diplomatic progress potentially putting further downward pressure on prices while renewed escalation could trigger a recovery.
DAX
- DAX 40 Price: The DAX 40 is trading higher at around 25,385 points during Monday morning's session.
- Business climate: Germany's Ifo Business Climate Index came in at 90.2 in October, slightly above the consensus forecast of 89.9 and the previous reading of 89.9. However, the assessment of current conditions declined to 88.8 from 89.5, while business expectations improved to 91.6 from 90.4, suggesting that companies remain cautious about current conditions but are becoming more optimistic about the outlook.
- Merz's statement: German Chancellor Friedrich Merz stressed the European Union's strategic interest in maintaining open access to international markets, highlighting the bloc's 450 million consumers in the context of cooperation with the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP).
- Infineon investments: German semiconductor manufacturer Infineon plans to invest €1.1 billion, equivalent to approximately $1.23 billion, in its Austrian site to expand production of power semiconductors for data centres.
- Volkswagen news: Volkswagen has started testing Level 3 autonomous driving technology on public roads in Hefei, in China's Anhui province, after receiving the necessary road test permit. The development represents another step in the automaker's efforts to advance autonomous driving capabilities in the Chinese market.
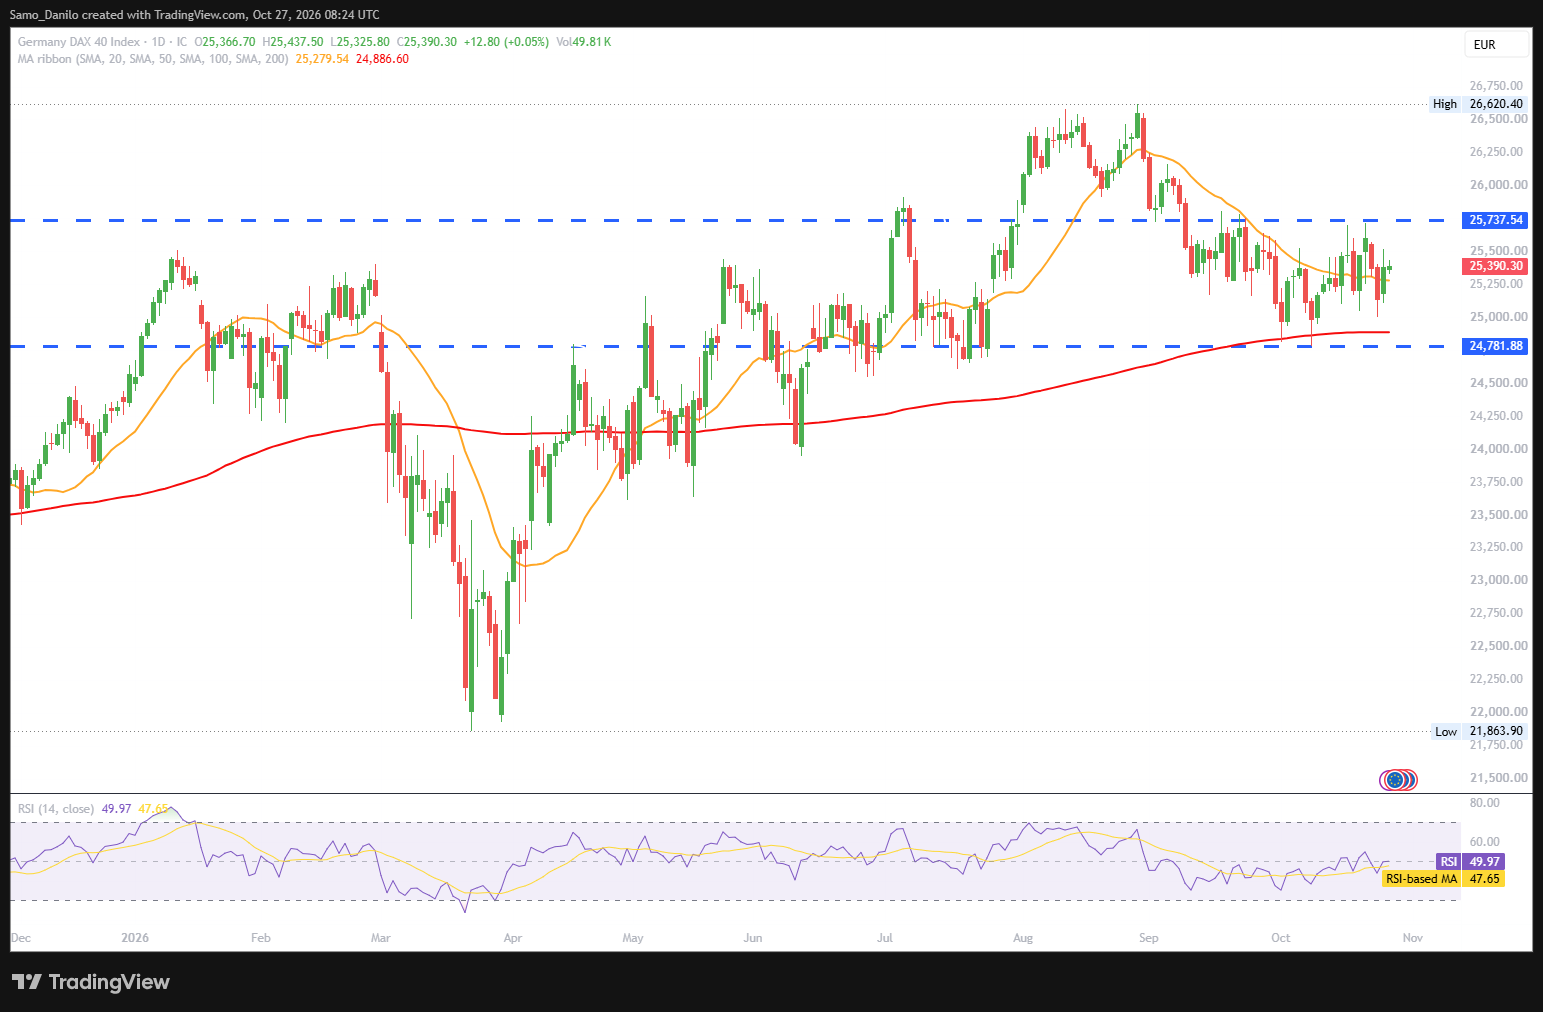
| SMA (20) | Slightly Falling | |
| RSI (14) | Slightly Falling | |
| MACD (12, 26, 9) | Slightly Falling | |
Closing statement: The DAX 40 is trading higher near 25,385 points, with Germany's improving business expectations and positive corporate investment developments providing support. In the near term, the index's direction will likely depend on incoming economic data, corporate developments and broader European market sentiment.